Last updated: October 2026
Most people ask a removal firm for a price and a date. Far fewer ask for an insurance certificate, and that is where trouble starts. This removal company insurance guide UK homeowners can use before booking explains who pays when a wardrobe slips on the stairs or a van scrapes a neighbour’s car, and how to check the paperwork yourself.
It covers the four types of cover a reputable firm should hold, what the law requires and what it does not, and the questions to ask before you pay a deposit. It is written with Greater Manchester moves in mind, from city centre flats to older terraced homes.
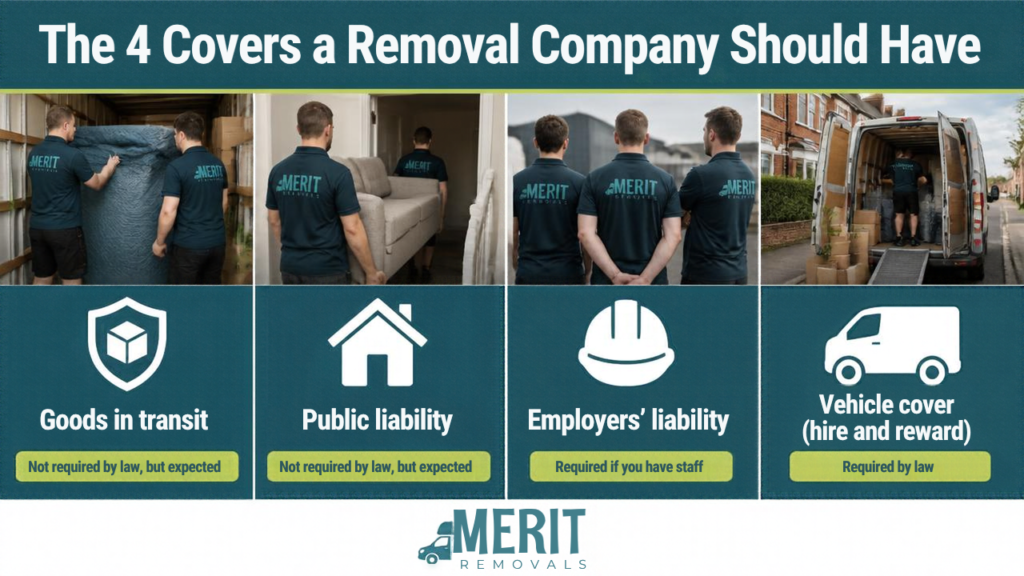
Quick answer: A reputable removal company should hold goods in transit insurance (for your belongings), public liability insurance (for damage to buildings and other people’s property), employers’ liability insurance of at least £5 million if it has employees, and vehicle insurance that covers carrying goods for hire and reward. Only the last two are required by law, so ask to see the certificates, check the limits, and read the liability clause in your contract before you pay a deposit.
In this guide
- Why removal company insurance matters more than the quote
- The four types of cover
- What the law requires and what it does not
- Limited liability, declared value and the underinsurance trap
- What is usually not covered
- Does your home contents insurance cover the move?
- Does BAR membership replace checking the insurance?
- How to check a removal company’s insurance step by step
- Manchester moves: where insurance questions come up most
- Protect your own claim
- What to do if something is damaged or lost
- Common mistakes homeowners make
- Practical tips before moving day
- Removal company insurance FAQs
- Key takeaways
Why Removal Company Insurance Matters More Than the Quote
A house move puts two kinds of risk on the table. The first is damage to your belongings: the sofa, the glassware, the piano. The second is damage to everything around them: the stairwell, the lift, the new hallway floor, the neighbour’s parked car. Different policies deal with each, and a firm can hold one without the other.
That is why the cheapest quote can turn out to be expensive. One cracked dining table or gouged doorframe can wipe out the saving, and if the firm has no cover behind it, you may be left chasing a small business for money it does not have. Price gaps between firms can reflect crew quality and cover as well as van size, which is worth remembering when you read our guide to removal company cost in Manchester.
If you are still deciding who to hire, our wider guide on how to choose a removal company in Manchester covers reviews, surveys and quotes. This article goes deeper on one question: is the firm properly insured?
Removal Company Insurance Guide UK: The Four Types of Cover
When someone says a firm is “fully insured”, they usually mean one of four different policies. Each protects something different, and only some are required by law.
| Type of cover | What it protects | Legally required for a removal firm? | What to ask to see |
|---|---|---|---|
| Goods in transit | Your belongings while they are in the firm’s care | No, but any reputable firm holds it | The limit, the exclusions and the rules on owner packed items |
| Public liability | Damage to buildings, lifts and other people’s property, and injury to the public | Not by law, but BAR members must hold it | The limit and the policy dates |
| Employers’ liability | Injury or illness claims from the firm’s own staff | Yes, at least £5 million if the firm employs anyone | The certificate and the insurer’s name |
| Vehicle (hire and reward) | The van or lorry when it is used to carry goods for payment | Yes | Wording that names carriage of goods for hire and reward |
Goods in Transit Insurance
Goods in transit insurance protects your belongings while they are in the firm’s care: being loaded, driven and unloaded. It is the cover that should respond if the van is stolen or crashes, or if the crew damages your furniture. It covers the contents of the vehicle, not the vehicle itself.
There is no legal requirement for a business to hold it, so you cannot assume it exists. Ask for the cover limit, whether it applies while items are carried through your home as well as in the van, and what it excludes.
Public Liability Insurance
Public liability insurance responds when the firm damages someone else’s property or injures a member of the public. Think of a scraped hallway wall, a cracked tile, a damaged lift or a dented neighbour’s car.
This cover is generally voluntary under UK law, according to guidance from the Health and Safety Executive, but members of the British Association of Removers must hold it at a level the association sets. Ask for the limit and the dates the policy runs.
Employers’ Liability Insurance
If a removal firm employs anyone, UK law says it must hold employers’ liability insurance of at least £5 million from an authorised insurer, as GOV.UK explains. The fine for going without is £2,500 for every day the firm is not properly insured, and the certificate has to be accessible to staff, for example on the firm’s website.
It protects the firm’s people rather than your belongings, but it still tells you something. A company that skips a legal requirement is one to be wary of. Ask how the crew who turn up on your day are engaged, because the rules differ for agency staff and freelancers.
Vehicle Insurance for Hire and Reward
An ordinary van policy does not cover a business that is paid to carry other people’s goods. That needs hire and reward cover, which is a legal requirement for carrying goods for payment. It insures the vehicle and the driver’s liability on the road, not the goods inside, which is why it sits alongside goods in transit cover rather than replacing it.
What the Law Requires and What It Does Not
The legal picture is less reassuring than most people expect. Employers’ liability cover and hire and reward vehicle insurance are compulsory. Goods in transit and public liability are not. A firm can trade legally with no cover for your belongings at all, which is why you need to ask.
Consumer law does give you a baseline. Under the Consumer Rights Act 2015, a service must be carried out with reasonable care and skill. If a removal firm falls short, you may be entitled to a remedy, such as a price reduction or compensation for damage it caused. That right exists whatever the firm’s insurance says.
Insurance decides whether a small company can actually afford to honour a claim. This article is general information, not legal advice.
Limited Liability, Declared Value and the Underinsurance Trap
Not every firm sells you insurance. Many offer a contractual liability instead, which is a promise to pay up to a set limit if they damage or lose something. The wording of that promise matters more than a headline claim that you are covered.
Published removal terms show how low a default limit can be. Figures of £40 and £50 per item appear in firms’ terms and in older BAR model conditions, and the cap usually applies unless you declare a value before the move. A £1,200 sofa damaged beyond repair could attract a payout nowhere near its value if you never declared it.
Declaring values brings its own trap. Many liability terms and insurance policies use an “average” clause. If you declare an item at £100 and it is really worth £200, a claim may be met at only 50 percent of the loss. Declare honest replacement values for the things that matter, and do not trim the figures to shave a few pounds off the price.
Questions That Expose the Real Level of Protection
- Is my cover insurance, standard liability or limited liability?
- What is the maximum payout per item and per move?
- Is there an excess, and who pays it?
- How and when do I declare the value of my belongings?
- What is the time limit for making a claim?
What Is Usually Not Covered
Even with good cover in place, some losses tend to fall outside it. Policies differ, so read this as a list of questions to put to the firm, not a guarantee.
- Boxes you packed yourself. Many firms and insurers decline claims for the contents of owner packed boxes, because they cannot check how well the items were wrapped. Glass that arrives broken with no sign of rough handling is the classic example. If you would rather avoid the argument, our packing service in Manchester puts the packing in the firm’s hands.
- Items you did not declare, or declared at too low a value.
- Jewellery, cash and important documents. These are commonly excluded or sub limited. Carry them yourself.
- Existing damage and wear, such as scratches, loose joints and items that were already fragile.
- Internal faults in appliances and electronics that cannot be traced to visible handling damage.
- Items moved by friends or family, or left unattended outside.
- Items the firm advised against moving. Our guide to what items removal companies cannot move explains why some things are refused or need special arrangements.
Does Your Home Contents Insurance Cover the Move?
Often, but not automatically. A GoCompare analysis of more than 400 contents policies found that 78 percent covered belongings during a house removal as standard, and another 11 percent offered it as an optional extra. The catch is that cover typically applies only when a professional removal firm carries out the move.
That makes the choice between a professional crew and a hired van more than a price decision. If you are weighing it up, our comparison of man and van versus a removal company in Manchester sets out the practical differences. Some man and van operators carry full cover and some do not, so the same checks apply to them.
Before moving day, phone your own insurer and ask:
- Does my policy cover the move itself, and does it require a professional firm?
- Does it cover theft, accidental damage or both while items are in transit?
- What are the limits for high value items?
- Are items covered if they spend time in storage between homes?
- Can cover at the new address start on completion day?
A removal firm’s insurance and your contents policy do different jobs and can work together. Treat them as layers, not alternatives.
Does BAR Membership Replace Checking the Insurance?
The British Association of Removers is the main trade body for the industry. Its Code of Practice, approved by the Chartered Trading Standards Institute, applies to UK based members handling furniture removals for private customers. Under it, members must offer you either insurance against loss or damage or another protection option, backed by liability insurance the member holds itself. They must also carry public liability insurance at a level the association sets.
The Code also requires contracts to draw your attention to limits of liability and the time limit for making claims. Complaints must be acknowledged within 3 working days, with an aim to resolve them within 8 weeks, after which you can use an independent dispute resolution scheme. If a member fails and you cannot recover a prepayment, the Advance Payment Guarantee Scheme may help.
That is a strong safety net, but it does not replace reading the certificate and the contract. Check membership on the BAR website rather than trusting a logo on a van. A firm outside BAR is not automatically unsafe, but you will not have the Code behind you, so the paperwork matters even more.
How to Check a Removal Company’s Insurance Step by Step
This is the most practical part of any removal company insurance guide UK homeowners will read. It takes about ten minutes and is best done while you compare quotes, not the week before the move. If you are still working out timings, see our advice on when to book a removals company.
- Ask for the certificates in writing. A reputable firm will email them without fuss. You want goods in transit, public liability, employers’ liability if it has staff, and the vehicle policy wording.
- Match the names. The company named on each certificate should match the company on your quote and contract. A certificate in a different name is a reason to ask questions.
- Check the dates. The policy period must include your moving day. An expired certificate is no protection at all.
- Read the limits. Compare the goods in transit limit with the replacement value of everything going on the van, not just the big items.
- Check the business description. It should cover furniture or household removals. If it describes something else, ask why.
- Check the insurer. Look the insurer up on the Financial Conduct Authority register to confirm it is authorised.
- Ask about exclusions in writing. Cover owner packed items, high value pieces, the excess and the claims time limit.
- Confirm it is live. If anything looks odd, contact the insurer or broker named on the certificate and ask them to confirm the policy is in force.
Questions to Ask Before You Book
- ☐ Who is the insurer, and what is the goods in transit limit?
- ☐ Does cover apply while items are carried through my home, not just in the van?
- ☐ What is the public liability limit, and does it cover damage to my property?
- ☐ Are all crew members covered, including casual or agency helpers?
- ☐ Will you accept liability for items I pack myself?
- ☐ How do I declare the value of high value items?
- ☐ What is the time limit for claims, and how do I make one?
- ☐ Can I have all of this in writing before I pay a deposit?
Red flags: a firm that will not share certificates, offers only verbal assurances, asks for a large cash deposit, shows a certificate in a different company name, stays vague about liability limits, or pressures you to book before you have seen the paperwork. Any one of these is enough to keep looking.
Manchester Moves: Where Insurance Questions Come Up Most
City Centre Apartments
Apartment moves involve lifts, loading restrictions and building management rules, as our guide to removals in Manchester city centre explains. Some buildings ask contractors for proof of insurance before they will book a lift slot, so check with your building manager early and request the certificates from your removal firm in good time.
Older Terraces and Narrow Stairs
Many older homes across Greater Manchester have narrow hallways, steep stairs and tight turns. That is where scuffed walls, chipped banisters and damaged doorframes happen, and it is public liability rather than goods in transit that responds. Ask what protection the crew uses for floors and walls, and what the policy says about damage to the property itself.
Student Moves
Student house moves often put several people’s belongings into one load, which can mean more than one claimant. Agree whose items are on the inventory and check the cover limit against the combined value. Our student removals guide for Manchester covers the practical side.
Pianos and High Value Pieces
Pianos and other high value items may need specific cover or a declared value. Our piano removal service and specialised removals pages explain how these jobs are handled. Whichever firm you use, ask for the item and its value to be written into the paperwork.
Protect Your Own Claim: Document Before, During and After
Good cover only helps if you can prove what happened. A little preparation makes any claim far easier.
- Take dated photos of valuable furniture, appliances and artwork on the morning of the move.
- List high value items with their replacement cost and serial numbers where they have them.
- Carry irreplaceable items yourself: passports, jewellery, laptops, hard drives and family keepsakes.
- Keep the quote, contract, inventory and insurance certificates together in one folder.
- Note any damage on the delivery paperwork before the crew leaves, and photograph it.
- Keep damaged items and their packaging so they can be inspected.
What to Do If Something Is Damaged or Lost
- Tell the crew leader and record it. Ask for the damage to be noted on the paperwork, and photograph it straight away.
- Find the claims time limit. Your contract should state it. Do not wait, because some firms give days rather than weeks.
- Make the claim in writing. Describe what happened, attach photos and proof of value, and ask for the insurer’s details and claim form.
- Use the complaints process. If the firm is a BAR member, it should acknowledge your complaint within 3 working days and aim to resolve it within 8 weeks. After that, the independent dispute resolution scheme is open to you.
- Get free advice. The Citizens Advice consumer service can guide you through your options, including on 0808 223 1133. If you paid by card, ask your card provider whether you can recover the money.
- Consider the small claims route. GOV.UK explains how to make a court claim for money if everything else fails.
Common Mistakes Homeowners Make
- Treating “fully insured” as a fact. It is a claim until you have seen the certificates.
- Never reading the liability clause. That one paragraph decides what you are paid.
- Declaring low values to cut costs. An average clause can punish you when you claim.
- Packing fragile and valuable items without checking the effect on cover. Ask first.
- Relying on reassurance from a sales call. If it matters, get it in writing.
- Assuming contents insurance still applies on a self drive move. Many policies expect a professional firm.
Practical Tips Before Moving Day
Ask for the insurance details to be written into your quote. It takes one line and removes any doubt later.
Value things at replacement cost. What it would cost you to buy again today, not what you paid years ago.
Walk the route with the crew. Pointing out tight corners and fragile items before loading starts reduces the chance of damage and of arguments about it.
Do a final walk through together. Check every room, the loft and the garage before the van leaves and again before the crew leaves the new address.
Removal Company Insurance Guide UK: Frequently Asked Questions
Do removal companies have to be insured in the UK?
Some cover is compulsory and some is not. A firm that employs staff must hold employers’ liability insurance of at least £5 million, and a vehicle used to carry goods for payment needs hire and reward cover. Goods in transit and public liability insurance are not required by law, but any reputable firm should have both.
What insurance should a removal company have?
Look for goods in transit insurance, public liability insurance, employers’ liability insurance if it has employees, and vehicle insurance covering hire and reward. Ask to see all of them, with limits and dates that cover your moving day.
Are my belongings covered if I pack the boxes myself?
Often not. Many firms and insurers decline claims for the contents of owner packed boxes because they cannot verify the packing. Damage clearly caused by the crew, such as dropping a box, is a different matter. Ask the firm for its position in writing before moving day.
How much goods in transit cover is enough?
Enough to replace everything on the van at today’s prices. Add up the replacement value of your contents, compare it with the policy limit, and ask how high value items should be declared.
What is the difference between limited liability and insurance?
Limited liability is a contractual promise to pay up to a set cap if the firm damages your goods, and the cap can be low. Insurance is a policy that pays out to a stated limit, often with options to declare higher values. Ask which one your quote offers.
Does my home contents insurance cover a house move?
It may. A GoCompare analysis of more than 400 policies found that most covered removals as standard, but typically only when a professional removal firm did the move. Check your policy and ask your insurer before moving day.
Does BAR membership mean I am fully insured?
No. BAR members must offer insurance or another protection option and hold public liability cover, but the level of protection still depends on your contract and the values you declare. Read the liability clause and the certificates even when the firm is a member.
Can I ask a removal company for a copy of its insurance certificate?
Yes, and you should. A reputable firm will send it without hesitation. Check the company name, the insurer, the policy dates and the limits.
What should I do if the removal firm damages my belongings?
Note the damage on the paperwork, photograph it, and make a written claim within the contract’s time limit. If the firm will not resolve it, use its complaints process, the independent dispute resolution scheme if it is a BAR member, or advice from Citizens Advice.
Key Takeaways
Here is the short version of this removal company insurance guide UK movers can bookmark for later:
- Four covers matter: goods in transit, public liability, employers’ liability and vehicle insurance for hire and reward.
- Only employers’ liability and hire and reward cover are legally required, so ask to see the rest.
- Read the liability clause, and declare honest values to avoid the average trap.
- Owner packed boxes, undeclared valuables and existing damage are the usual gaps.
- Check your home contents policy, because it may expect a professional firm.
- BAR membership adds real protections, but it does not replace reading the paperwork.
Ten minutes of checking before you pay a deposit is the cheapest protection a move will ever give you.
Get a Clear Quote and Clear Answers About Cover
Moving in Manchester or Greater Manchester? Tell us about your move and we will send a clear quote. Whoever you choose, ask to see the paperwork, and feel free to put the same questions from this guide to us.
Request your free quote, explore our removal services in Manchester, see how we work on our about page, or check our pricing page first.